Key Factors That Influence the Value of Fixed Assets in Malaysia
Fixed asset valuation involves more than an asset’s original purchase price or accounting depreciation. Its physical condition, remaining useful life, technology, market demand and intended use can all affect its current value. In Malaysia and across the rest of the ASEAN countries, these factors also need to be considered alongside applicable accounting and tax requirements.
Many businesses view fixed asset valuation as a simple routine, relying strictly on historical costs and standard depreciation. However, field audit research compiled by Dartmouth College indicates that up to 94% of operational spreadsheets contain errors.
Overlooking real-world asset shifts leading to economic obsolescence as an e.g can lead to inflated balance sheets or complications during structural impairment testing. Truly understanding an asset’s value requires looking at the whole picture.
Here are the key factors that shape real value and the balanced approaches used to measure them.
Key Considerations When Assessing Fixed Asset Value
1. Physical Condition and Maintenance
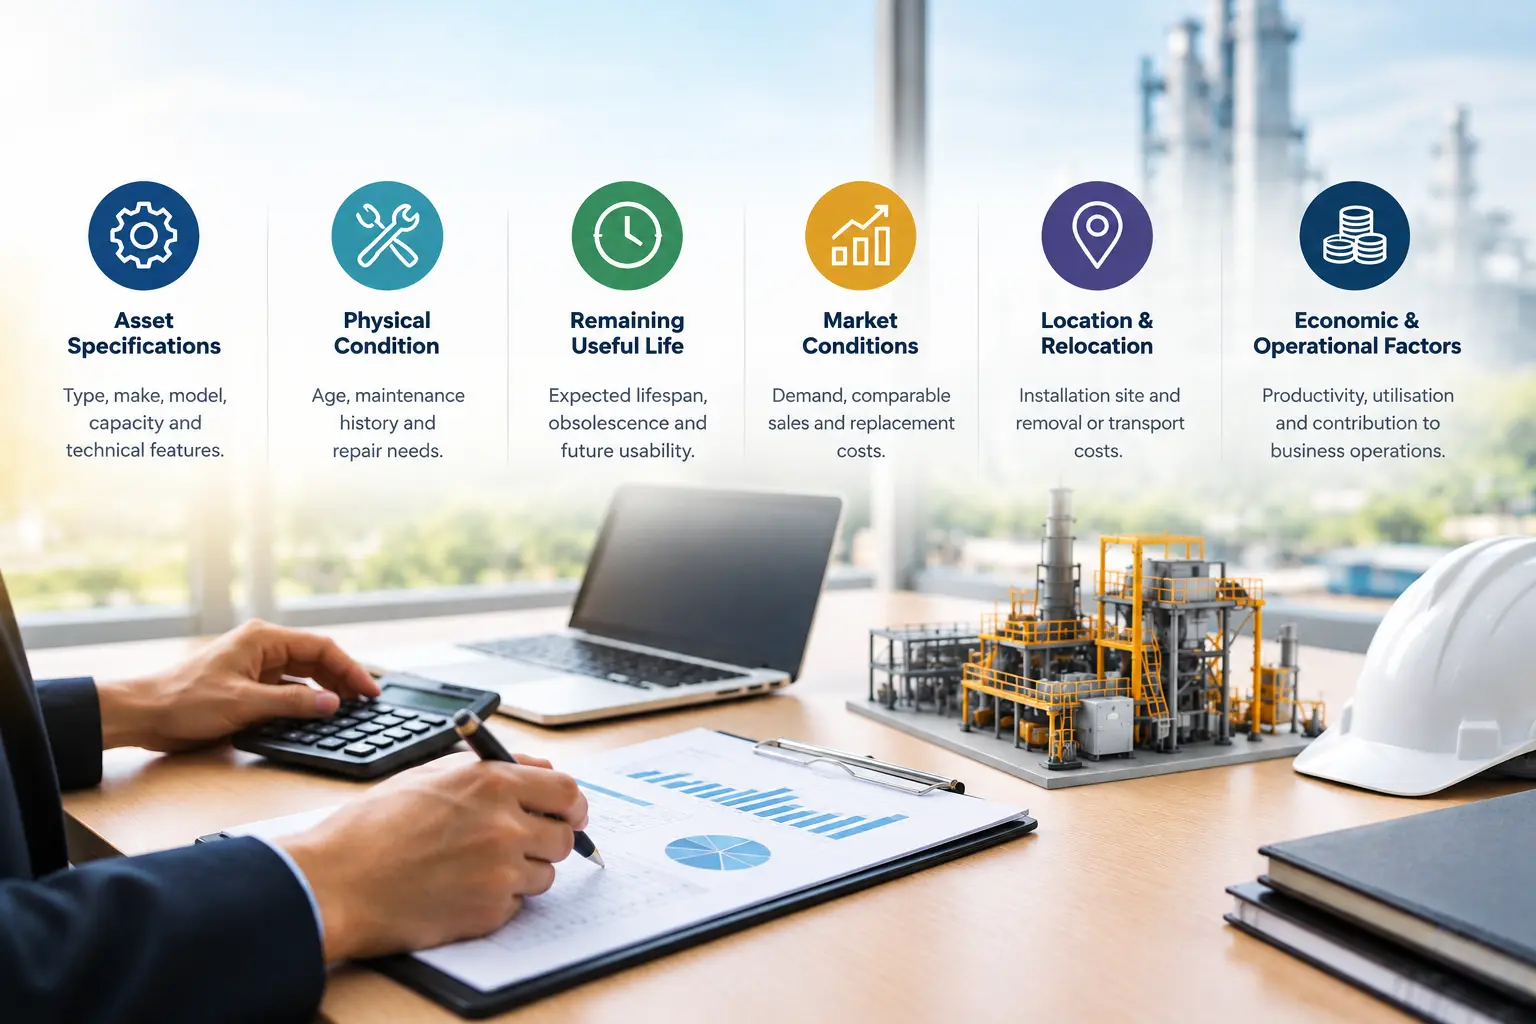
The physical condition of an asset is one of the most direct factors affecting its value. Age, wear and tear, usage and maintenance history can indicate how much useful life remains and whether the asset can continue operating as intended.
Well-maintained equipment may retain more of its value than a similar asset that has experienced prolonged use or inadequate servicing. Maintenance records can therefore provide important evidence when assessing the condition and expected longevity of plant, machinery and other fixed assets.
For Malaysian businesses operating in manufacturing, construction, logistics and industrial sectors, evaluating the condition of equipment is particularly important when determining its current value and remaining economic life.
2. Technology and Functional Obsolescence
An asset can lose value even when it remains physically operational. Changes in technology may make older equipment less efficient, less compatible with current systems or unsuitable for evolving operational requirements. This is known as functional obsolescence.
Newer equipment may offer greater automation, efficiency or capabilities, reducing demand for older alternatives. The extent to which an asset remains fit for its intended purpose is therefore an important consideration in fixed asset valuation.
3. Market Conditions and Asset Demand
Market conditions can significantly influence the value of fixed assets, particularly where comparable transactions are available.
Factors such as industry demand, the availability of similar assets, resale activity, import costs and broader economic conditions can affect market value. Currency movements and changes in equipment supply may also influence the cost of acquiring replacement assets in Malaysia and in the ASEAN region.
Valuation can be more challenging when assets are highly specialised or comparable transactions are limited. For unique machinery, infrastructure and industrial equipment, a more detailed assessment of the asset’s characteristics, replacement cost and economic usefulness may be necessary.
4. Asset Characteristics and Location
The specifications and characteristics of an asset can affect how it is valued. Capacity, configuration, technical specifications, operating capabilities and suitability for a particular application may distinguish one asset from another.
Location can also be relevant, particularly for large equipment and fixed assets where transportation, installation, accessibility and local market conditions influence value. In Malaysia and in rest of the ASEAN countries, these considerations can be particularly relevant for specialised industrial assets where replacement or relocation may involve significant costs.
5. Accounting and Tax Considerations
The accounting and tax treatment of fixed assets can influence how their value is reported and assessed.
Malaysian businesses may apply the Malaysian Financial Reporting Standards (MFRS) or the Malaysian Private Entities Reporting Standard (MPERS), depending on their reporting requirements and eligibility. Under the applicable framework, the accounting treatment for property, plant and equipment may involve the cost model or, where permitted, the revaluation model.
The appropriate valuation therefore depends not only on the asset itself but also on the purpose and reporting framework for which the valuation is required.
6. Purpose of the Valuation
The purpose of a valuation can determine the relevant basis and the information that needs to be considered. A valuation prepared for financial reporting, such as Purchase Price Allocation (PPA) or impairment testing, may have different requirements from one undertaken for financing, Mergers and Acquisitions (M&A) or restructuring.
Understanding the intended use at the outset helps ensure that the valuation addresses the relevant requirements and produces a conclusion appropriate to the assignment.
Fixed Asset Valuation Methods
Choosing the right method is never a one-size-fits-all process. The right approach depends entirely on the type of asset, the available market data, and the specific goals of the assessment.
● Cost Approach
The cost approach considers the cost of replacing or reproducing an asset with one providing it with an asset offering similar utility in Malaysia or any other country. Adjustments are made for physical deterioration, functional obsolescence and economic obsolescence, considering local construction costs and market conditions.
● Market Approach
The market approach uses evidence from comparable transactions or market prices. It is particularly useful where there is sufficient and reliable market data for similar assets.
● Income Approach
In Malaysia like in other countries, this method may be suitable for income-generating assets such as commercial properties, rental buildings and business assets, provided reliable financial projections and market data are available.
● Asset-Based Approach
For asset-heavy businesses, an asset-based approach can consider the value of the underlying assets and liabilities. This may be relevant when assessing businesses with substantial plant, machinery, infrastructure or other tangible assets.
Why Work With Spring Galaxy?
Fixed asset valuation requires a detailed understanding of physical condition, technical specifications, market evidence and applicable financial reporting requirements. Relying on a single measure may not adequately reflect the factors that influence an asset’s current value.
Spring Galaxy applies structured fixed asset valuation methods to assess these factors and develop valuations suited to different business requirements. Its experience working with Big 4 and mid-tier accounting firms, financial advisors, local corporates and MNC’s supports a considered approach to complex valuation assignments.
For businesses operating in Malaysia as well as other ASEAN countries, a well-supported valuation can assist with financial reporting, impairment testing, financing, mergers and acquisitions (M&A), purchase price allocation (PPA) and restructuring.
Conclusion
The value of a fixed asset can change significantly throughout its useful life. Physical condition, maintenance, technological developments, market demand, asset characteristics and the purpose of the valuation all influence the final assessment.
Selecting an appropriate valuation method helps businesses develop a more accurate understanding of their fixed assets and supports the financial and strategic decisions for which the valuation is required.
The main factors are an asset's physical condition and maintenance history, technology and functional obsolescence, market conditions and demand, the asset's characteristics and location, the applicable accounting and tax treatment, and the purpose of the valuation.
Age, wear and tear, usage and maintenance records indicate how much useful life remains and whether an asset can keep operating as intended. Well-maintained equipment may retain more of its value than a similar asset that has had prolonged use or inadequate servicing, which is why maintenance records are important evidence in a valuation.
Functional obsolescence occurs when an asset that still works becomes less efficient, less compatible with current systems or less suited to current operating needs because of technological change. Newer equipment may offer greater automation or capability, which reduces demand for older alternatives and can lower the older asset's value even when it is physically sound.
The common approaches are the Cost Approach (the cost of replacing the asset, adjusted for physical, functional and economic obsolescence), the Market Approach (comparable transactions or market prices), the Income Approach (for income-generating assets, where reliable projections are available) and the Asset-Based Approach (for asset-heavy businesses).
Yes. The purpose determines the relevant basis of value and the information required. A valuation for financial reporting, such as purchase price allocation (PPA) or impairment testing, can have different requirements from one prepared for financing, mergers and acquisitions (M&A) or restructuring, so the intended use should be confirmed at the start of the assignment.
Businesses commonly commission a fixed asset valuation for financial reporting under MFRS or MPERS (including where the revaluation model is permitted), impairment testing, purchase price allocation, financing, mergers and acquisitions, and restructuring. Spring Galaxy's valuation team can help you confirm the right scope and approach for your situation.
